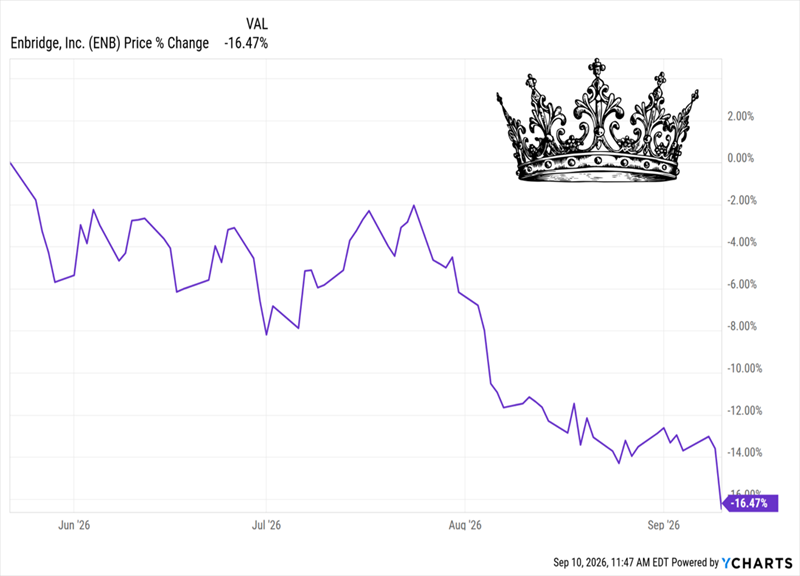
One of our favorite pipeline plays—Enbridge (ENB)—has taken a tumble. It’s set up a sweet buying opportunity.
We can thank rising rates (with an “assist” from overdone trade war fears!) for this opening.
Here’s the state of play with this one, which I’ve nicknamed the “natty” king because, despite its Canadian domicile, it ships 20% of the natural gas consumed in the US.
- The stock yields a gaudy 5.6%.
- Enbridge is a “toll booth” on North American energy consumption, collecting fixed rates for the use of its pipelines and storage facilities, no matter what oil and gas prices do.
- The stock has returned 56% for us since we bought it in March 2023.
- Its payout has jumped 77% in the last decade (more on that below).
Right now, the natty king is showing an attractive blend of strength and value. Even with that 56% total return, the stock is still down—off 16% on a price basis from its May highs. That’s a big part of our opportunity here:
The “Natty” King’s (Temporary) Fall
Beyond rates, some investors see the company as a potential trade-war victim. That’s in part because Enbridge is also a major oil shipper: Its 8,600-mile Mainline system, an important part of its operations, ships Canadian crude to refineries in the US Midwest.
But these folks are missing the point. For one, to date, oil and gas have been exempted from the trade spat.
That’s by design: The administration doesn’t want to raise fuel costs, and the Canadian side doesn’t want to antagonize its resource-producing western provinces. Plus, those Midwest refineries are set up to process Canadian “heavy” crude, and that can’t be easily changed.
Yes, Venezuela produces a crude similar to Alberta’s. But as we discussed last week, the country’s battered oil infrastructure needs many years, and billions of dollars, of investment.
As I write this, Enbridge’s project backlog has grown to $41 billion Canadian . And it’s deploying $10 billion Canadian in growth capital this year alone. Current projects stretch into the 2030s.
It’s already making news on this front: Last Thursday, Enbridge announced a US$2.55-billion deal to buy a 75% stake in the 1,050-mile, 460,000-barrel-per-day Pony Express pipeline, which ships crude from the US Rockies to the key storage hub at Cushing, Oklahoma.
The deal also covers 51% of the Powder River Gateway system, which can ship up to 240,000 barrels a day, as well as other storage and marketing assets.
It’s a cash deal, but the company will come up with some of the purchase price through a C$2.6-billion share offering. The resulting dilution prompted a selloff last week. We’re fine with that, as Enbridge expects the deal to add to its cash flow right away, after it expects to close the deal later this year (pending regulator sign-off, of course).
Finally, Enbridge said CEO Greg Ebel will retire December 31. Michele Harradence, who’s been with the company since 2014 and is now president of Enbridge’s gas-distribution and storage operation, will take over. Her familiarity with the business (and the fact that Ebel will advise her until next May) tees up a smooth transition.
Steady Payout Growth, With a Potential Currency “Kicker”
Now let’s talk dividends. Earlier this year, the company treated us to a payout hike—its 31st consecutive increase.
And that payout is well-covered, with Enbridge kicking out $3.88 (Canadian) in annualized dividends and guiding to$5.70 to $6.10 in distributable cash flow per share in 2026. The midpoint of that estimate translates to 66% of DCF going out as dividends—very reasonable for a “toll booth” like ENB.
Take a look at this payout picture—I’m sure you’ll see something interesting (beyond the rarity of a 5.6%-yielding stock hiking payouts 77% in 10 years):
Enbridge’s Payout Surfs FX Rates
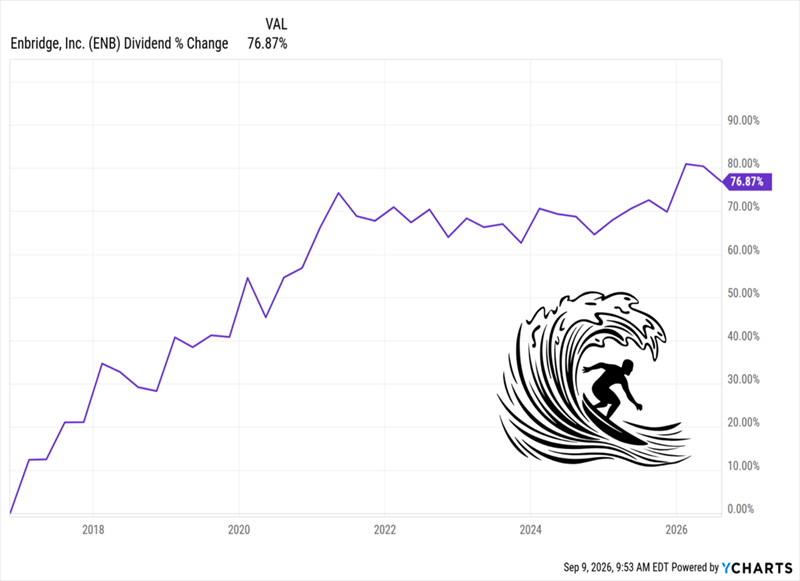
As a Canadian company, Enbridge issues dividends in “loonies” (shorthand for the country’s loon-emblazoned one-dollar coin). That’s why you don’t see the clean “dividend staircase” we’re used to in our stocks.
As a result, the US dollar’s strength versus the loonie weighs on our payouts. But that could be a plus in the long run. Here’s why: In the US, the Fed’s target range is 3.5% to 3.75%, compared to the Bank of Canada’s 2.25% policy rate. The gap between the two central banks’ rates is a big reason for the greenback’s strength versus its Canadian cousin.
The Iran situation is a driver of inflation in both countries. But it will end at some point. When it does, the Fed will have more room to cut than the Bank of Canada, by virtue of its higher “starting point.”
As rates fall, they should put upward pressure on shares of “bond proxy” utilities and pipelines. They could also weigh on the greenback, potentially boosting our dividends when they’re converted to US dollars.
To be sure, the trade war could push rate cuts down the road, but we’re fine with that: While we wait, we’re locking in Enbridge’s 5.6% payout.
(One thing to note before I wrap up here: Since Enbridge is a Canadian company, US investors face different tax treatment in the form of 15% withholding on dividends, though an offsetting tax credit may be available. This explainer lays out the details.)
Where does all this leave the natty king? While the rest of the world gets riled up by the headlines, Enbridge hardly notices. It simply goes on quietly collecting tolls on the rising tide of oil and gas flowing through its pipes.
Enbridge Pays Us 5.6%. This One Yields 12% (and Pays Monthly)
As I just said, Enbridge is a top play on overdone fears around trade and rates. The stock’s payout growth lets us build on the 5.6% dividend on a buy made now.
In short, the Canadian “natty king” is one of those stocks you can buy now and lock away forever.
It’s not the only one.
The other top pick I want to tell you about now fits that mold also. It’s a special type of fund that pays high dividends—this one yields 12% now, with payouts rolling our way monthly.
This fund is so unloved (thanks, again, to overdone, short-term thinking around rates) that it’s trading well below the value of its underlying holdings. Buy now and you lock in that 12% payout ($12,000 in yearly dividends on every $100K invested) and position yourself for price gains as rates eventually move lower.
In the meantime, we’re happy to wait—especially as we’re getting a 12% payout while we do!
Click here and I’ll tell you more about this 12%-yielding pick and give you a free Special Report that unmasks it. You get its name, ticker, a full breakdown of its holdings, the scoop on its manager (who was previously named Fund Manager of the Year by Morningstar) and more.