Can you hear me now, income investors? Verizon (VZ) wants to know.
It’s been a roller-coaster October for the telecom. Given its always-high yield, I know our dividend fans are often considering Verizon, asking, “Is it a good buy now?”
Well, its price is down and profits are up. So that’s a promising start!
Why the bargain though? (Or as my kids ask me when they watch commercials: Daddy, what’s the catch?)
On October 8, Elon Musk made a move! Potential competitor SpaceX (SPCX) agreed to buy nationwide spectrum in a move that would bring Musk into the telecom world. The next day was Verizon’s worst since 2002, with the stock down 10%. Yet weeks later the company announced its best third quarter for phone customers in five years!
So which is it? Is the panic justified, or do we buy the pullback?
Let’s break down the fear. SpaceX is in talks to lease space on 80,000 cell towers, which is about half of those in the country. Half!
These are negotiations, not yet signed deals, but SpaceX has been active, signing spectrum deals worth well over $20 billion in about a year. And money is no object. If you haven’t heard, SpaceX recently went public, so it has more access to capital markets. It raised $75 billion, the biggest IPO ever!
Now here’s the thing: SpaceX doesn’t have to win the wireless war to make life harder for Verizon. Simply by showing up with a cheaper option, Musk and Co. can make pricing more difficult.
Dish Network, remember them? Dish basically tried to be the fourth carrier, and its wireless business went bust doing that. That said, it does not have SpaceX’s Elon-sized checkbook. Musk tells Wall Street he’s going to do something awesome, and the suits shovel him money. Not so awesome if you compete!
But Verizon is cheap, too! It trades at a bargain 9-times earnings. There aren’t many P/Es under 10 for real live companies out there today. And the 6.3% dividend? The company’s cash flow covers it two times over.
And it’s bringing on new customers, with about 406,000 net new phone customers versus only 44,000 a year ago.
So, what’s not to like?
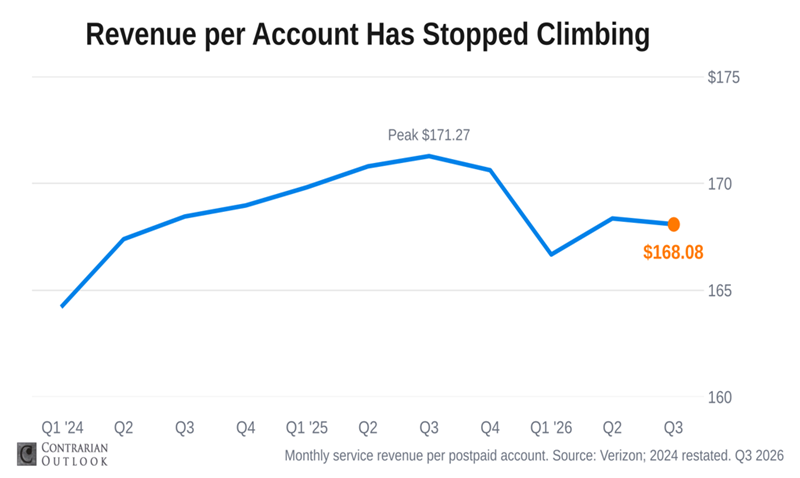
Well, in addition to the Elon overhang, Verizon’s average revenue per account is down by about 2%. So, while the company is winning customers, it’s charging each one a bit less. (Which means when my kids ask me what the catch is on the Verizon ad, I reply there’s not enough of a “catch” for the company to boost what each customer pays!)
So far, cost cuts have buoyed Verizon’s profits. But there’s a limit to frugality and if SpaceX competition brings pricing pressure, look out.
Also, the company has taken on about $14 billion of extra debt this year, and its interest costs are up 19% year over year. The stock is cheap for a reason! It’s the same old Verizon: a dividend that pays but gives most of the gains back in price pullbacks!
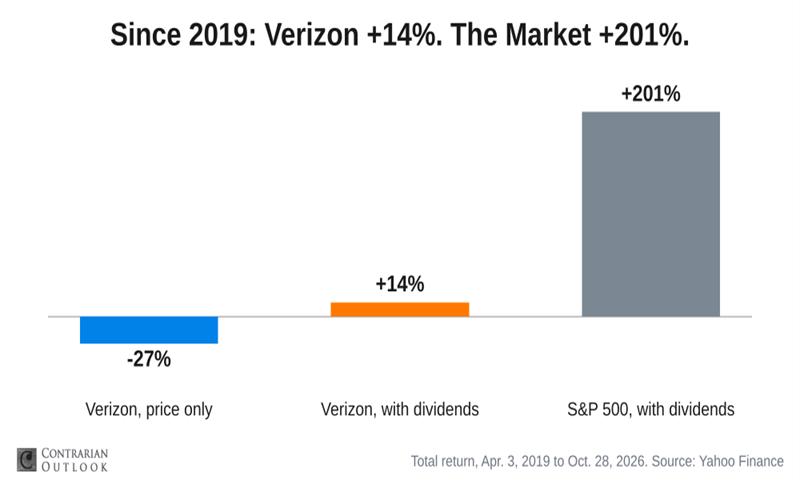
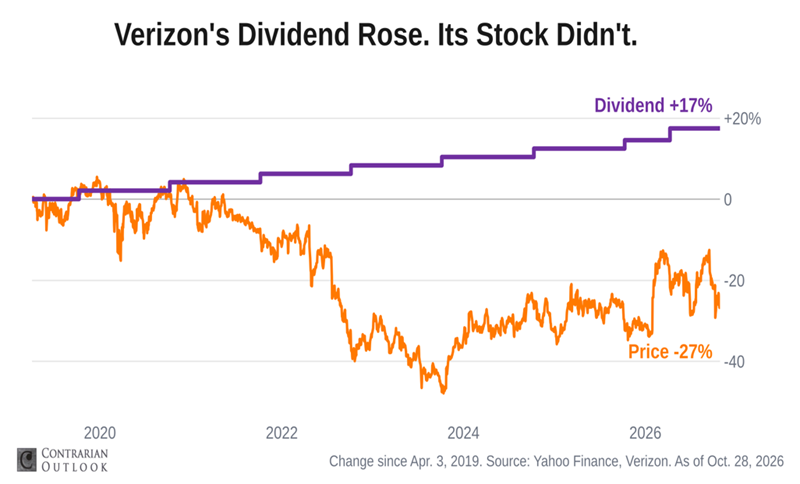
In a 2019 interview, I told a reporter that yes, Verizon’s dividend was safe, but the stock had little upside. Since then, through Oct. 28, it’s down 27%. Yes, the dividend got paid and raised every year, but the total return, with dividends reinvested, has been about 14%—a stingy 1.7% per year. Little upside indeed!
Dividend Magnet fans know my rule: payouts act like magnets, pulling stocks higher (dividends up) or lower (dividends cut), for better or for worse. Yet Verizon proves that there are exceptions to every rule. If a Dividend Magnet isn’t magnet-ing, it’s usually because of a business headwind, and that’s exactly the case for Verizon. Seven years later, the stock price hasn’t followed the rising dividend. This “broken magnet” is still a pass.
So no, Verizon isn’t a better deal today than in 2019, when it yielded 4.1%, even though it pays 6.3% today—about 50% more! The divvie only helps us if the stock price is flat or rising, and the latter depends on profits growing. Today, revenue per Verizon account is slipping, and a new deep-pocketed rival is circling.
What could change? If SpaceX walks away from the tower talks, or if Verizon’s revenue per account turns around and starts increasing again. Or if Verizon’s price continues to decline, there’s a point at which it will be so cheap it’s attractive. But today I don’t love it, and to be honest, I don’t even like it.
Stay focused. The key number to watch is revenue per account. Verizon needs to introduce some “catch” to capture more money from each customer. Until it does, this apparently safe dividend remains an “avoid.”
So where to invest your dollars for dividends today?
Subscribe now on a risk-free basis to Contrarian Income Report and I’ll send you the details on Friday morning! Plus, receive my latest monthly dividend machine research (with dividends over 11%) right away.