Fair to say that if you’re saving for (or are in) retirement, two things are critical:
- High yields, for income now.
- Fast (and ideally accelerating) dividend growth, for gains and higher income down the road.
If you’re like many people, you’re probably nodding along with that.
Most investors would agree with it. Problem is, most don’t follow through! They get distracted by stocks whose payouts are low (or nonexistent) and go nowhere. Or they sit in ETFs like the State Street SPDR S&P 500 ETF Trust (SPY), which yields a sad 1% now.
Both of the above are dangerous because, if you need cash, it’s only a matter of time before you’ll be forced to sell into a 2022-like mess to get it. That’s a big risk to run when there are sturdy 7%+ payers that can take on some of your monthly costs now, without a hefty upfront investment.
That’s the “high-yield-now” part of the equation we opened with. Then you sprinkle in part 2: Dividend stocks whose payouts aren’t only growing—they’re accelerating.
As we discuss regularly here, there’s a connection between dividend growth and price gains. I call it the “Dividend Magnet” because a rising dividend tends to pull the stock price up with it.
I can give you example after example, but here are three that jump out over the past 10 years:
- Lowe’s Companies (LOW): Dividend up 257%, price up 219%
- NextEra Energy (NEE): Dividend up 187%, price up 202%
- Abbott Labs (ABT): Dividend up 138%, price up 166%
Then, beyond rapid growers like these, we have the sweetest setup of all in dividend-land:
A 7%-yielder that grows its payout, too.
These “unicorns” are rare finds, but they are out there. The stock I’m going to show you today is one of them. And its 7.7% yield and steady dividend growth are just the start.
This one also pays dividends monthly. That not only saves us from having to sell into a downturn to get the cash we need—it pays us right in line with our bills, too.
Plus, this company—a business development company (BDC) called Main Street Capital (MAIN)—hands out regular “supplemental” dividends on top!
It could be a holding of our Hidden Yields dividend-growth advisory, but it’s found a home in our Contrarian Income Report service, which focuses on the big payouts we need right now.
Check out this pretty payout (and share price) picture:
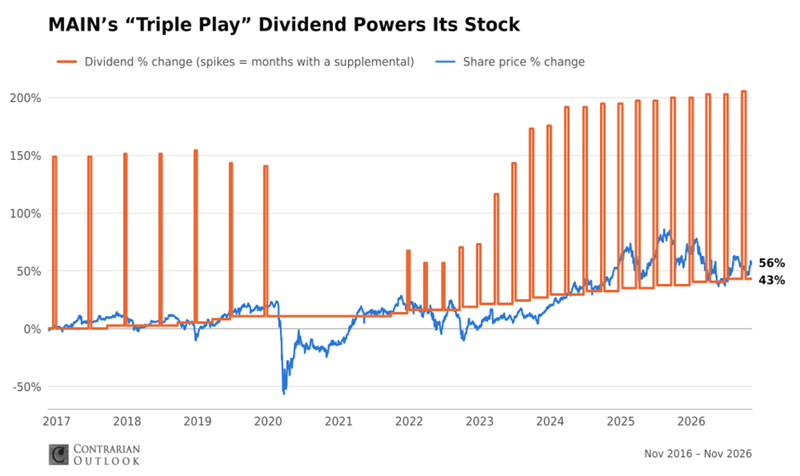
Let’s start with the regular dividend, which yields that 7.7% (including the supplemental payouts I’ll get to in a second) and, yes, the regular dividend comes our way monthly. MAIN has raised the payout twice this year, with one hike declared in May and a second in November, for a total increase of 3.8%.
And as you can see, over the last decade, the payout has risen some 43%. That’s actually on the slower side for MAIN, which prudently held its regular dividend steady (and paused its supplementals) through the pandemic years.
Then there are the spikes you see above. Those are the supplemental payouts. MAIN just declared its 21st straight quarterly supplemental, payable in December.
MAIN can do this in part because it’s a business development company (BDC)—a lender to smaller companies across the US. Think of a thriving regional manufacturer, a specialty healthcare provider or a niche business-services firm—companies that are successful but still have plenty of runway to grow.
MAIN also provides straightforward loans to slightly larger “middle-market” firms and even manages assets and offers advisory services, rounding out its approach to creating income from solid, Main Street businesses (sorry, couldn’t resist!)
As a BDC, it’s required to distribute at least 90% of its taxable profits as dividends to stay exempt from corporate income tax. And the regular payout is well covered: MAIN’s third-quarter distributable net investment income (NII, the BDC version of cash flow) came in at $0.96 a share, comfortably above the $0.795 it paid in regular monthly dividends. (The supplementals draw on undistributed income MAIN has built up.)
MAIN Collects on Borrowers, Passes the Cash to Us
This sweet “triple play” dividend—high yield, monthly payouts and dividend growth—brings another underappreciated perk: payouts big enough to “repay” our upfront buy price in a reasonable amount of time.
Consider that, since we bought MAIN in our May 2025 issue of Contrarian Income Report, it has delivered a total return (dividends plus price gains, in other words) of 19.4%.
But it’s also done something else: paid us a total of $6.71 a share in dividends. We paid $53.83 a share—so we’ve already “recouped” about 12.5% of our purchase price.
Hold a high, reliable payer like this one for long enough (around 13 years in all, assuming today’s payouts, supplementals included, hold steady and not counting any payout growth) and you’d get your entire purchase price back in dividends alone.
A BDC With Two Growth “Engines”
Yes, this is a particularly uncertain time for small- and middle-market US companies, with whipsawing policy changes out of Washington and overall “sticky” inflation increasing costs.
However, AI offers potential for big efficiency gains, which will help companies keep up on their loan obligations. Moreover, MAIN holds mainly floating-rate loans, whose income grows when rates rise, as they have lately.
Of course, that income falls when rates move lower, as they eventually will. That’s where another aspect of MAIN’s approach comes in, which is uncommon among BDCs: In addition to loans, it holds equity stakes in the companies to which it lends. And since stocks tend to benefit when rates fall, these holdings help offset any “rate drag” on its loans.
This essentially gives MAIN two growth engines instead of one. It’s also why I see this company’s payouts continuing to grow in the years ahead, potentially cutting down the roughly 13 years you’d need to be “repaid” on a buy made today.
High yields now, dividend growth down the road: MAIN checks both boxes we opened with. It sends us a dividend “paycheck” every month, too!
This Pays Us MORE Than 7.7%. I’m Talking 9%+ Dividends (Paid Monthly)
MAIN is a terrific “triple play” dividend—and it’s one of the holdings in my 9% Monthly Payer Portfolio.
As the name says, this portfolio is built on high payers (9% on average) that pay us every single month.
That’s 9X what the S&P 500 pays, so our “payback” builds faster, too.
That’s our whole strategy: Collect dividends big enough to cover our bills so we can leave our nest egg intact. And we can do it without investing a seven-figure sum.
I’d like to show you my full 9% Monthly Payer Portfolio now, starting with my top 3 picks. They’re in my free Special Report, “Monthly Dividend Superstars: Yields Up to 16.2% With Double-Digit Upside.”
Sixteen -point-two percent!